
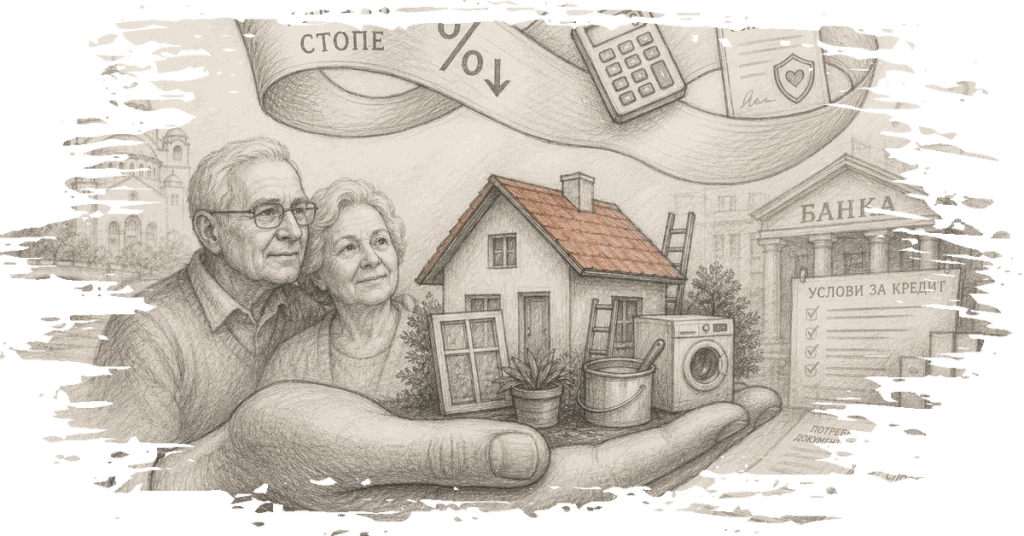
Pensioners in Serbia are now able to access cash loans under more favorable conditions, marking a significant shift in banking policies that traditionally favored employed individuals. This development allows pensioners to obtain loans for various purposes, such as home renovations, purchasing appliances, or assisting family members, with banks offering special loan products tailored to their needs.
The National Bank of Serbia (NBS) has played a pivotal role in this shift by introducing measures that facilitate cash loans of up to 1,000,000 dinars specifically for pensioners. These loans come with lower interest rates compared to previous offerings. As of April 2026, the average interest rate on newly approved cash loans has decreased to 8.3%, a reduction of about one percentage point from the previous year. This is expected to ease the financial burden on pensioners seeking credit.
However, the conditions for pensioners to obtain these loans vary significantly between banks. Factors such as the pensioner’s age, the amount of pension received, and their creditworthiness are considered. While the general age limit for loan repayment is set at 75 years, some banks allow borrowing beyond this age with additional security, such as life insurance or property collateral.
Life insurance has become a common requirement for pensioners applying for loans, serving as a safeguard for the borrower’s heirs against unforeseen expenses in the event of the borrower’s death. This insurance can be paid either as a lump sum or in installments, and in some cases, the bank may cover the insurance premium.
The NBS has also stipulated that the nominal interest rate for these loans should be three percentage points lower than the average rate offered by the bank, with a minimum rate of 10.5%. These loan products are expected to be available for at least 12 months, with no processing fees charged to the applicants.
Despite the more favorable terms, pensioners are advised to carefully consider the total cost of the loan, including the effective interest rate and other associated fees. For instance, a loan of 500,000 dinars with a nominal interest rate of 10.5% over three years would result in monthly payments of approximately 16,250 dinars, totaling around 585,000 dinars over the loan period. Extending the repayment period to five years would reduce the monthly payment to about 10,750 dinars, but increase the total repayment to approximately 645,000 dinars, with interest costs amounting to around 145,000 dinars.
The introduction of these loan products reflects a broader trend towards accommodating the financial needs of older citizens in Serbia. However, there are concerns about the long-term sustainability of such loans and the potential financial risks for pensioners who may face difficulties in repayment due to limited income. Financial experts emphasize the importance of understanding the full implications of borrowing and the need for careful financial planning to avoid future financial strain.
Overall, while the new loan conditions provide pensioners with greater financial flexibility, it is crucial for potential borrowers to thoroughly assess their financial situation and the terms of the loan to make informed decisions.